Titan shares dip 5% post Q2 update as brokerages maintain bullish stance
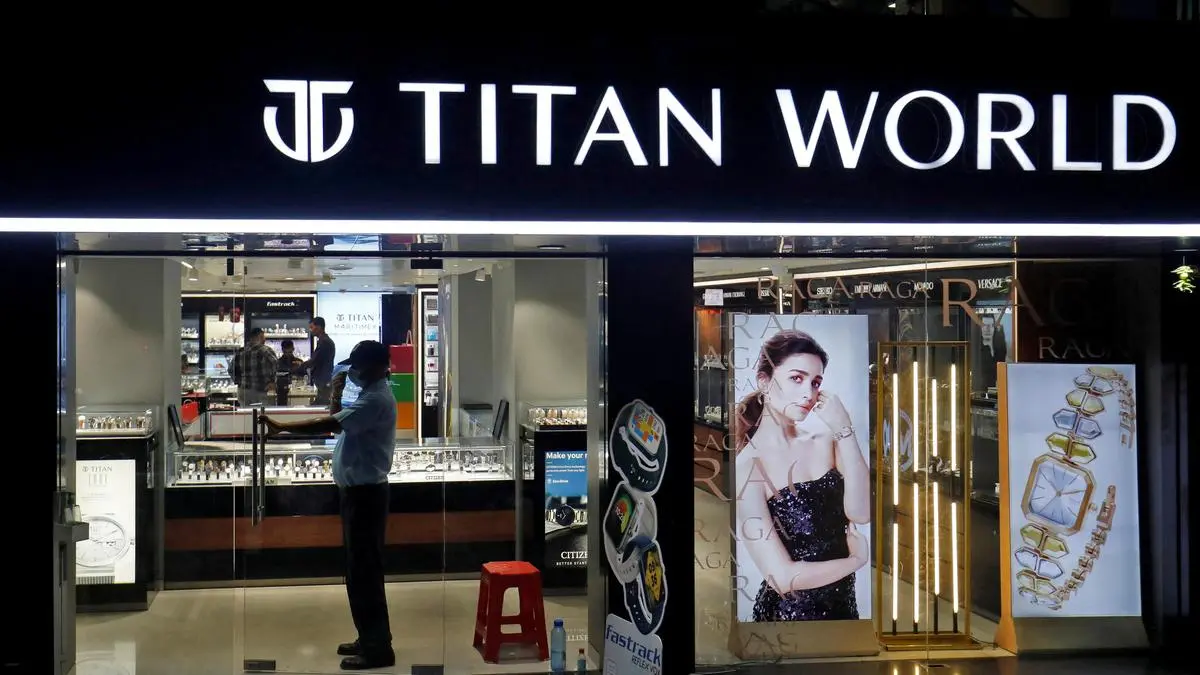
Titan shares fell nearly 5 per cent on Wednesday following the company's Q2FY27 business update, which showed domestic jewellery growth of 21 per cent year-on-year, below some brokerage estimates. The stock traded at ₹4362 on the NSE at 9.46 am, after touching a low of ₹4335.60, compared with the previous close of ₹4,550.
Titan Company’s consumer businesses registered a 25 per cent year-on-year growth in Q2FY27. During the quarter, the company added 78 stores on a net basis, expanding its combined retail network to 3,758 stores.
The jewellery portfolio across all brands recorded 21 per cent year-on-year growth. Consumer demand remained healthy for most of the quarter, with some softening towards the close due to the shift in the festive calendar to Q3FY27. Studded jewellery grew in the early thirties, supported by the 'Festival of Diamonds' and brand-level promotions, while plain gold jewellery grew 20 per cent year-on-year. Investment-led coin demand declined in the high single digits year-on-year from a high base.
Buyer growth at the portfolio level was in the mid-single digits, while average ticket sizes increased by double digits.
The watches business reported 30 per cent year-on-year growth, with analog watches growing in the early thirties and the smart watches segment recovering with high single-digit growth. EyeCare delivered 28 per cent year-on-year growth. Among emerging businesses, Fragrances grew in the mid-thirties, Women’s Bags grew in the twenties, and Taneira recorded high single-digit growth.
Citi retained its buy rating on Titan with a target price of ₹5700, noting that domestic jewellery growth excluding bullion was around 20 per cent year-on-year, below its 27 per cent estimate, but attributing the shortfall to the festive shift to Q3FY27 and weaker investment-led coin demand rather than a demand slowdown. It estimated ex-coin growth at 24-25 per cent and highlighted that buyer growth remained in the mid-single digits while average ticket size grew by double digits.
CLSA maintained an outperform rating with a target price of ₹5590, observing that domestic jewellery growth of 21 per cent year-on-year was above its consensus expectation of 19.3 per cent. It also highlighted 30 per cent growth in watches and 28 per cent growth in EyeCare.
HSBC retained its buy rating with a target price of ₹5510, stating that Titan reported lower-than-expected Q2 sales partly due to the shift in festive timing, while the mix was expected to improve given lower gold coin sales and a higher studded jewellery share. It trimmed its jewellery revenue estimate by 1 per cent.
JPMorgan maintained an overweight rating with a target price of ₹5540, noting that Q2FY27 revenue was below expectations, with domestic jewellery growth moderating to 21 per cent year-on-year due to softer buyer growth, a high single-digit decline in gold coins, and consumption deferment linked to the festive shift into Q3. It also highlighted 32 per cent revenue growth at CaratLane, along with acceleration in Watches and EyeCare growth to 30 per cent and 28 per cent, respectively, and expected the stock reaction to be negative following the Q2 revenue miss.
Market Spider rewrites market reports for information only—not investment advice. Trading in securities involves risk of loss.